

Moving Home
Moving home is exciting, but there's plenty to think about when it comes to your mortgage. From finding out how much you could borrow to understanding what happens to your existing mortgage, we're here to make things easier.
At Burrows Financial Services, we'll explain your options, help you find a suitable mortgage and keep things moving throughout the process.


Moving home? Let's make the mortgage side easier.
Moving to a bigger home, downsizing or looking for somewhere new? We'll take the time to understand your plans and explain your mortgage options in clear, straightforward terms.
We can help you find out how much you could borrow, discuss what happens to your existing mortgage and look at the most suitable options for your next home, so you can move forward with confidence.
If you're thinking of staying in your current home and reviewing your existing mortgage instead, you can also explore our remortgage options.
How much could you borrow when moving home?
When you're thinking about moving, one of the first things you'll want to know is how much you could afford to spend on your next home.
The amount you may be able to borrow will depend on your income, regular outgoings, existing financial commitments and personal circumstances. The equity in your current property can also make a difference to the deposit you have available.
We can help you work out what may be affordable before you start viewing properties, giving you a clearer idea of your options.

Factors lenders consider
As well as the equity in your current home, mortgage lenders will also look at a range of factors when assessing how much you could borrow.

Can you take your existing mortgage with you?
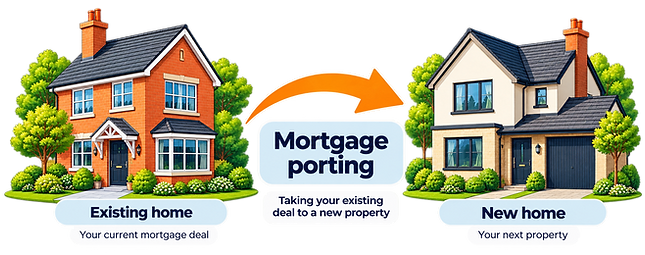
If you're moving home before your current mortgage deal ends, you may be able to take your existing mortgage deal with you. This is known as mortgage porting.
Porting can allow you to keep your existing interest rate and avoid an early repayment charge, depending on your lender's rules and the circumstances of your move.
However, it's not always as straightforward as transferring your mortgage from one property to another. Your lender will usually need to reassess your affordability and approve the new property.
If you need to borrow more, the additional amount may be arranged on a separate mortgage deal, potentially at a different interest rate.
We'll look at whether porting your mortgage makes sense or whether arranging a new mortgage could be a better option for you.

Porting your mortgage is subject to your lender's criteria, affordability assessment and approval of the new property.

What if you need a new mortgage when moving home?
If porting your existing mortgage isn't possible, or it doesn't offer the best option for your circumstances, you may need to arrange a new mortgage for your next home.
This could involve paying off your current mortgage when you sell your property and taking out a new deal with your existing lender or a different one.
There are a few things worth considering:
-
Early repayment charges: If you're still within a fixed or discounted deal, your lender may charge a fee for repaying your mortgage early.
-
Interest rates: A new mortgage could have a different interest rate, which may affect your monthly repayments.
-
Mortgage fees: Arrangement, valuation and other fees may need to be considered when comparing deals.
-
Your borrowing needs: Moving home may mean borrowing more, borrowing less or changing your mortgage term.
We'll compare the available options, explain the costs and help you understand which approach may be most suitable for your move.
What costs should you budget for when moving home?
As well as your deposit and monthly mortgage payments, there are a number of other costs to consider when moving home.
The exact amounts will depend on your circumstances, but it's worth budgeting for the following:


Estate agent fees
If you're selling your current property, remember to budget for estate agent fees.
Legal fees

Legal costs for buying your new home and selling your existing property.
Stamp duty

Depending on the purchase price and your circumstances, Stamp Duty may be payable.
Surveys

Surveys and property valuations can help you understand the condition and value of your new home.
Mortgage fees

Some mortgage deals have arrangement, valuation or other lender fees.
Removal costs

Remember to budget for removals, storage and other practical moving expenses.
How we help you through the moving home process
Moving home involves more than arranging a mortgage. There's often a property to sell, a new home to find and several people involved in keeping everything on track.
We'll help you understand your mortgage options, explain what needs to happen next and keep you updated as things progress.

We'll take the time to understand your plans and help you work out what you may be able to borrow before you commit to your next property.
Once you're ready, we'll help prepare and submit your mortgage application, deal with lender queries and keep you informed as your application progresses.
We'll also stay in touch as you move towards completion, helping with mortgage-related questions and liaising with the other professionals involved where appropriate.
Our support doesn't stop when your mortgage offer arrives. We're here to help you get to moving day.
WHY CHOOSE US

Mortgage advice that's
about more than finding a deal
Moving home can involve a lot of organising, especially when you're selling one property and buying another. Having someone you can speak to when questions crop up can make a real difference.
At Burrows Financial Services, you'll deal directly with Brad and Kim. We'll take the time to understand your plans, explain your mortgage options clearly and keep you updated as things progress.
We're based on the Fylde Coast and help people moving home across Poulton-le-Fylde, Blackpool, Lytham St Annes, Preston and the surrounding areas.
And because life doesn't always fit around office hours, we offer evening and weekend appointments too.